New reality in the home insurance market: political conflict risks move from the list of exceptions to standard conditions
For many years, the fundamental principle in the Lithuanian property insurance market has been that acts of war, terrorist acts, sabotage, riots and other outbreaks of political or mass violence have been considered a standard insurance exclusion. These risks have traditionally been considered extremely difficult to predict, so insurers have left them outside the scope of standard protection. Previously, only very large business clients or cargo owners transporting assets through high-risk regions of the world could request an extension to the insurance contract and remove these exclusions. However, the dynamics of geopolitical processes in recent years have irreversibly changed this established insurance provision.

Geopolitical shift and technological evolution
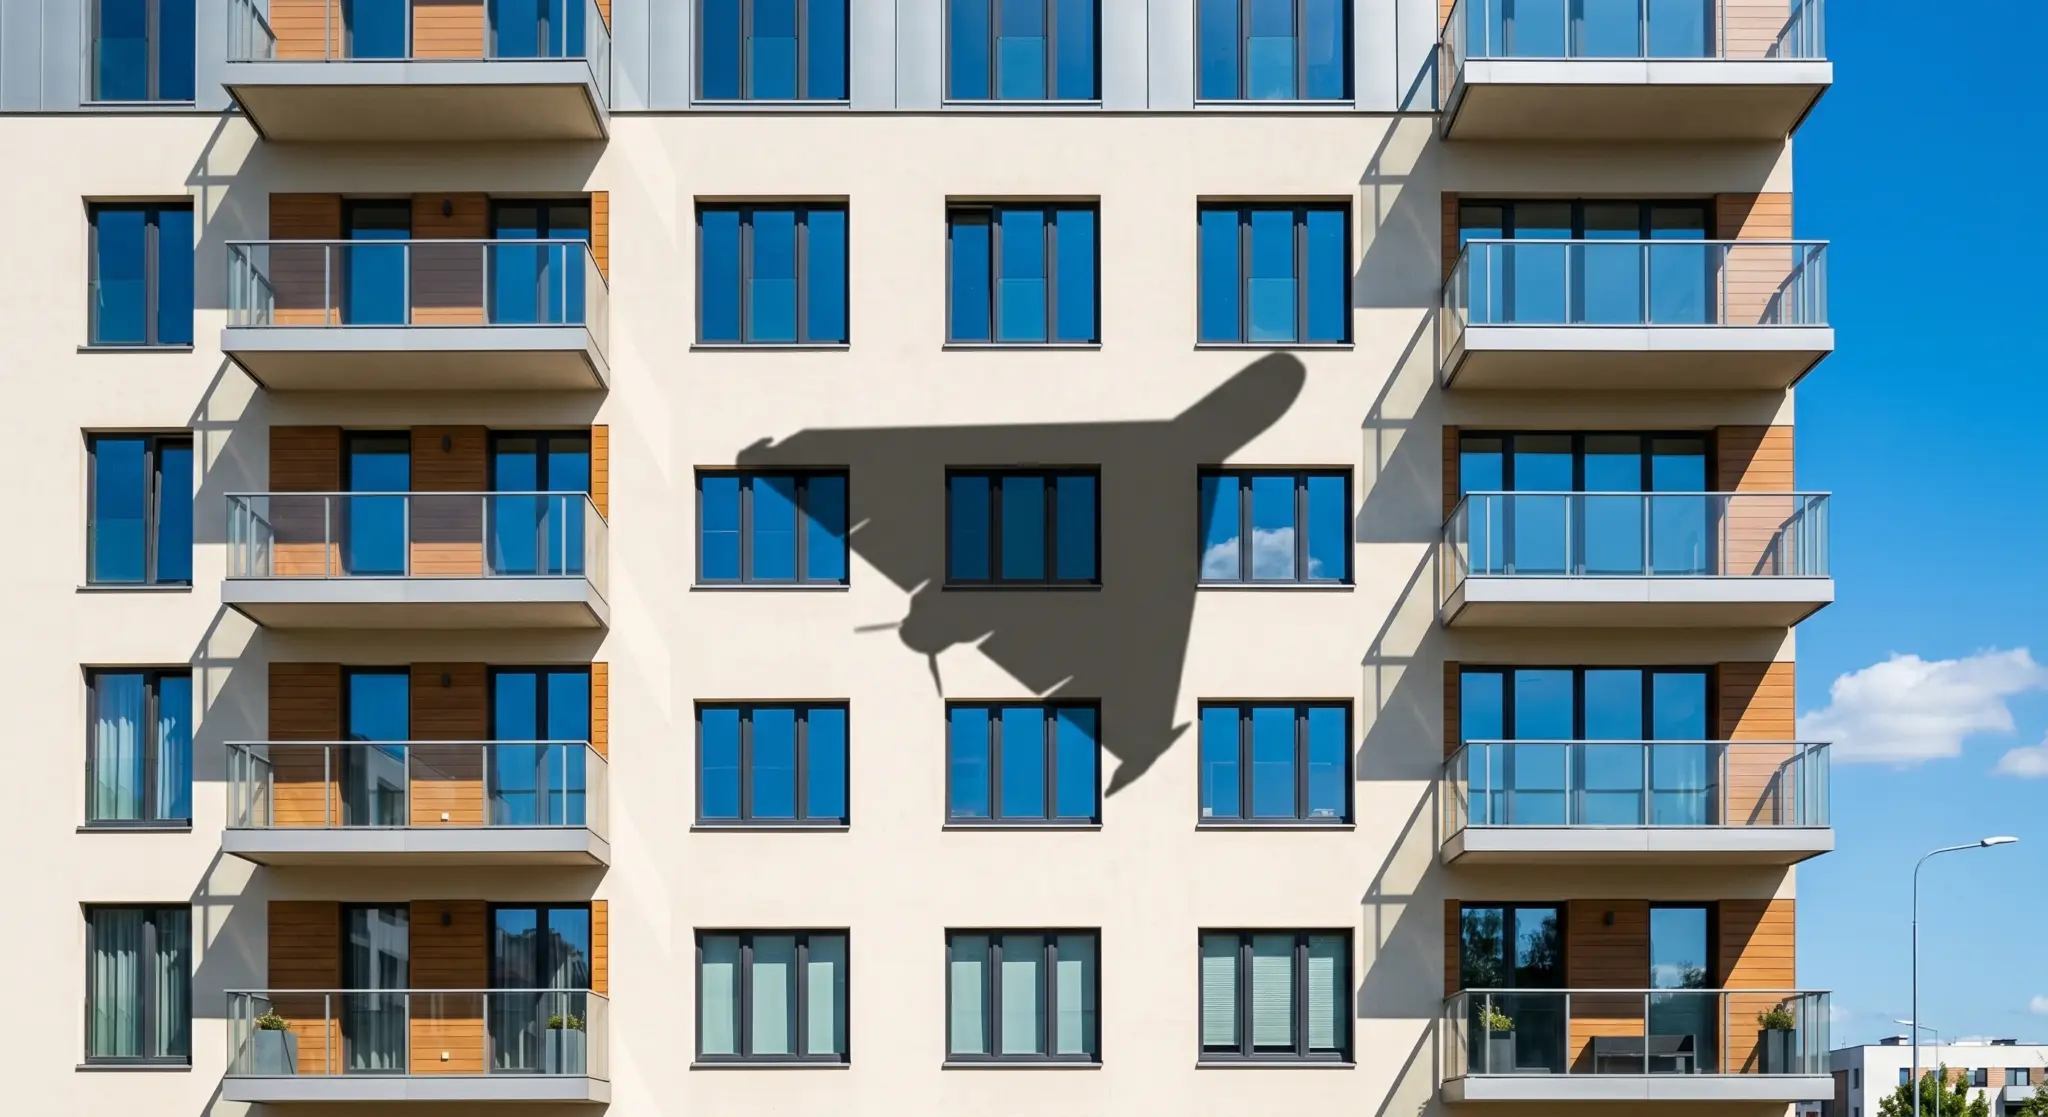
Today’s geopolitical tensions in the region, manifestations of hybrid warfare, and the astonishingly rapid development of combat and military drone technologies have turned the risks of political conflicts and the losses associated with them into a very real threat to every resident of Lithuania. If earlier we learned about explosions and drone strikes only from foreign news columns, now they have become a real risk for local real estate.
Against the backdrop of this new reality, the country’s largest insurer, Lietuvos Draudimas, was the first on the market to offer a solution to private clients – the opportunity to protect themselves from losses caused by political conflicts with home insurance. The timing of the introduction of this product was not chosen by chance and demonstrates a lightning-fast reaction to the security situation: the announcement of the new protection appeared immediately after an air emergency was declared in Lithuania due to the real threat of combat drones. According to Simonas Lisauskas, CEO of Lietuvos Draudimas, in conditions of growing uncertainty, residents’ expectations for home security are changing, therefore the leading company has taken on the responsibility to respond to the changing reality.
Essential terms and conditions for insurance against political conflict risks

The new terms and conditions of “Lithuanian Insurance” that came into effect on June 1, 2026 fundamentally change the approach to non-insurable events. Here are the most important aspects that you must know when evaluating this market innovation:
- Inclusion mechanism: This protection is mandatory and automatically included in all newly concluded and renewed (extended) residential home insurance contracts. Holders of existing valid contracts are not left out – they can additionally purchase this extension as an addendum to the contract.
- Covered risks: Protection is activated if the home or household property is damaged, destroyed or lost due to a terrorist act, sabotage, riots, strikes, malicious damage for political reasons, as well as due to uprisings, revolutions, rebellions, coups d’état and unconventional or civil war, including damage caused by military drones.
- Indemnity limits: The insurance indemnity limit directly depends on the type of property. The maximum limit is up to 200,000 EUR for an apartment, and up to 500,000 EUR for a house (including cottages or parts of a house). It is important to note that this payment cannot in any case exceed the market value of the housing itself or the total sum insured specified in the contract.
- Fixed price: The price of this additional protection for residents is fixed and amounts to EUR 9.90 per year.
However, when assessing the conditions from an expert’s perspective, it is necessary to pay attention to the logical exceptions provided. Insurance coverage will not be valid if the losses arise from a large-scale war in which nuclear superpowers (China, France, the Russian Federation, the UK and the USA) are directly involved. Also, damage caused by the effects of nuclear, chemical or biological weapons, confiscation or seizure of property by government institutions and the interruption of utility services (electricity, water, gas supply) is not covered.
Market context: a bold and right move by the insurer
In order to objectively assess this innovation, it is necessary to link it to the general context of the Lithuanian insurance market in 2026. This year brought additional financial obligations to homeowners – an additional 10 percent security fee was added to home insurance contract premiums, which goes to the state. At the same time, we see that the annual number of home insurance contracts in the Lithuanian market is growing slowly, so insurance premiums can mainly grow only from periodic premium indexation.
In such a rather inert market, burdened with additional fees, Lietuvos Draudimos’ decision to offer mandatory additional protection together with an additional fixed premium of EUR 9.90 is a bold and ambitious step.
In my opinion, this step is absolutely correct from both a social and business point of view. For the client, this additional 0.005% of the insured amount, an annual premium, is practically an imperceptible amount in the insurance basket. However, in return, the resident receives assured peace of mind and real financial protection against risks that seemed impossible to insure for an ordinary consumer just yesterday. This allows the insurer not only to demonstrate its role as a market leader and social responsibility, but also to generate an additional premium stream for the high-quality management and reinsurance of these specific risks.
The relatively low price sends a very important signal to the end user – the world’s major reinsurers today consider our region to be sufficiently safe and are willing to assume these risks at a reasonable rate. However, this financial ecosystem is extremely sensitive to geopolitical fluctuations. If the security situation in the region were to change, it is very likely that this reinsurance (and with it the service to the user) would instantly become more expensive, or such protection would become unavailable on the market again.
Other insurers find themselves at a serious strategic crossroads: wait for complete clarity on the geopolitical situation, risking losing market share, or spend an already depleted portion of their revenues on adequate reinsurance and hope that customers will agree to pay more for it.

Marius Jundulas
- Also read

The potholes on the roads are already gaping.
Even the most careful driver may not notice a pothole hidden in a puddle or in the darkness of the night. Fortunately, everything ends with
Driving abroad: how to prepare for a car trip around Europe?
Learn how to prepare for a family road trip around Europe: what documents are needed, how to prepare the car, and why travel insurance is

Fire safety recommendations for Christmas trees and home decorations
Firefighters receive calls every year due to sparking or burning light garlands, flaming wreaths, or fires caused by candles. Therefore, it is essential to follow

Bare ice, black ice and slush – dangerous winter phenomena on Lithuanian roads
Black ice, slush and slush are the most dangerous winter phenomena on the roads. Find out how they differ, how they form and how to

When do you renew your compulsory car insurance?
40% of drivers hesitate about when to renew their insurance. Find out why it’s not worth delaying and how to avoid risk and financial losses.

Travel insurance becomes mandatory when traveling to Georgia from 2026
According to the Georgian Tourism Law, travel medical insurance becomes mandatory for all foreign tourists entering the country.